AFR – Alex Gluyas
Ewan Galloway is portfolio manager of Perennial’s Global Resources Trust and is co-portfolio manager of the firm’s $314 million Strategic Natural Resources Trust.
Why are you closing the Strategic Natural Resources Trust to new investors and what’s been the secret to the portfolio’s big returns?
The science behind the optimal fund size is pretty loose. We’re acutely aware of the well-trodden path where a fund enjoys inflows on the back of good performance, only to become too big, suffer poor performance and then spend a painful couple of years right-sizing the ship.
For that reason, we’ve closed the fund at a level which is probably a touch below what we think we can manage effectively. There are plenty of reasons why a fund’s performance may suffer, we wanted to ensure that having too much money wasn’t one of them.
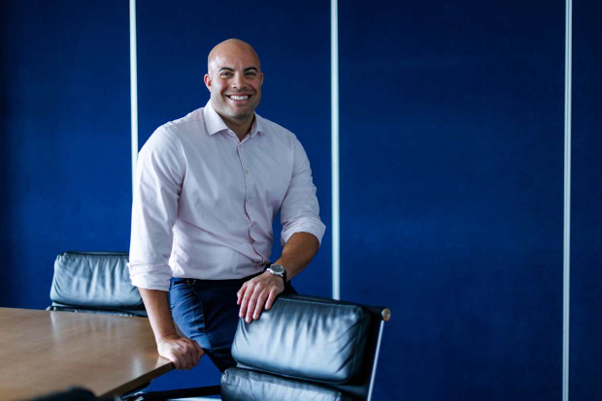
Ewan Galloway will helm Perennial’s freshly launched Global Resources Trust. Oscar Colman
We operate in the most inefficiently priced sector of the market, and all any fund manager does is exploit those inefficiencies. Some recent wins include Ora Banda, Southern Cross Electrical and Almonty Industries, which have all performed well and remain core holdings.
Your largest exposure by end of June was gold. Are you expecting prices will retest their record?
Whether it’s this year or next, the structural drivers for gold remain in place. It’s interesting to watch the market focus shift from alternatives to the US dollar as a store of value to a fixation on the timing of the next move in US interest rates. That ended on July 31 when we got a reminder – by way of the yen intervention – of how sensitive the US is to its rates being at the highest in 20 years. It could be argued that the US lending money to Japan to avoid a sale of US treasuries is quantitative easing by proxy. At least this seems to be the view of the gold market and the price has bounced accordingly.
We like producers with a strong operational track record, like Capricorn Metals and Agnico Eagle, who benefit from operational leverage, in what is still a historically elevated price environment for gold, paired with near-term upside from brownfield expansion.
July was a tough month for the fund. What changes have you made?
Undoubtedly, July was a painful start to the year. The key mistake was not leaning back into oil when hostilities flared up in Iran on July 7, the same way we did in March.
However, we reassessed our portfolio, exited some of our lower conviction ideas tied to the semiconductor trade and used the proceeds to take advantage of some clear dislocations in the market particularly in gold, copper, rare earths and energy infrastructure.
We’ve added to existing positions in Capricorn Metals, Brazilian Rare Earths and Almonty Industries. Ultimately, we believe that the outlook for resources remains extremely positive as increasing demand comes up against a depleting asset base.
Which commodity are you most bullish on over the next 12 months, and what is your top stock pick?
We really like energy infrastructure. Demand for power is ramping up at a significant rate that is being driven by the energy transition, artificial intelligence and clean energy on top of general industrial growth, with gas a key beneficiary.
Our core exposure to this theme is Gaztransport & Technigaz, which is a French-listed designer of the cryogenic membrane containment systems for LNG tankers. They have a near monopolistic market share, supplying 98 per cent of membranes to large carriers built from 2015 to 2024.
Not only are they benefiting from the growth in LNG demand, but they have also improved margins over the past five years to their highest level since 2018. Finally, their balance sheet remains extremely healthy, having been net cash since their IPO in 2014 while maintaining a dividend payout ratio of at least 80 per cent.
Perennial is launching a new fund. What is the opportunity, and what stocks will you be targeting?
The Global Resources Trust is building on the successful track record of the global sleeve of the Strategic Natural Resources Trust and aims to invest in large cap commodity stocks, specifically those exposed to the energy transition, clean energy and AI infrastructure.
The rationale behind the global focus, which allows us to go up to 100 per cent offshore, is that within Australia the S&P/ASX 200 Resources Index is dominated by iron ore and coal which, while excellent cash cows, don’t have the same positive long-term growth prospects like uranium, copper or energy infrastructure.
It’s clear that in large caps, the best pure play exposure to the fastest growing commodities is offshore. It’s also worth acknowledging that Australia is becoming harder to invest in. Increased taxes, rising power costs and a deteriorating industrial relations environment mean that offshore assets are looking increasingly attractive in the fight for capital allocation.
We like the outlook for energy infrastructure, copper and gold with key exposures being Gaztransport & Technigaz, Siemens Energy, Hudbay Minerals and Agnico Eagle.
Are there any books, podcasts or TV shows that you’d recommend?
I’ve got three kids under five and some change, so I’m in the parenting equivalent of the hurt locker. Still, I’m finding the time to slowly work my way back through James Baldwin’s If Beale Street Could Talk. On the podcast front, I’m hooked on the Business of Sport. It’s a cracking deep dive into the financial permutations of sport at all levels and combines two of my favourite things in life; niche financial analysis and sport.
What is your favourite local restaurant?
Colombo Social in Enmore is a standout with the beetroot bhajis and curry goat sure-fire winners.
Licensed by Copyright Agency. You must not copy this work without permission.